A buyer reached out to our team over the weekend with a practical question: “What could I afford if I wanted to spend about $3,100 to $3,200 a month?” It’s a good starting point for understanding Southern Maryland home affordability. Before you set a maximum price on your home search, you need to know what that monthly budget will cover and how much cash you want to use upfront.
What Can a $3,200 Monthly Budget Buy?
In the video, we used $300,000 to nearly $500,000 to illustrate how widely buying power can vary around the same monthly budget. Where you land depends on the loan type, down payment, interest rate, and costs tied to the property. Your income, existing debts, and other financial commitments also affect what a lender may approve and what you’ll feel comfortable paying.
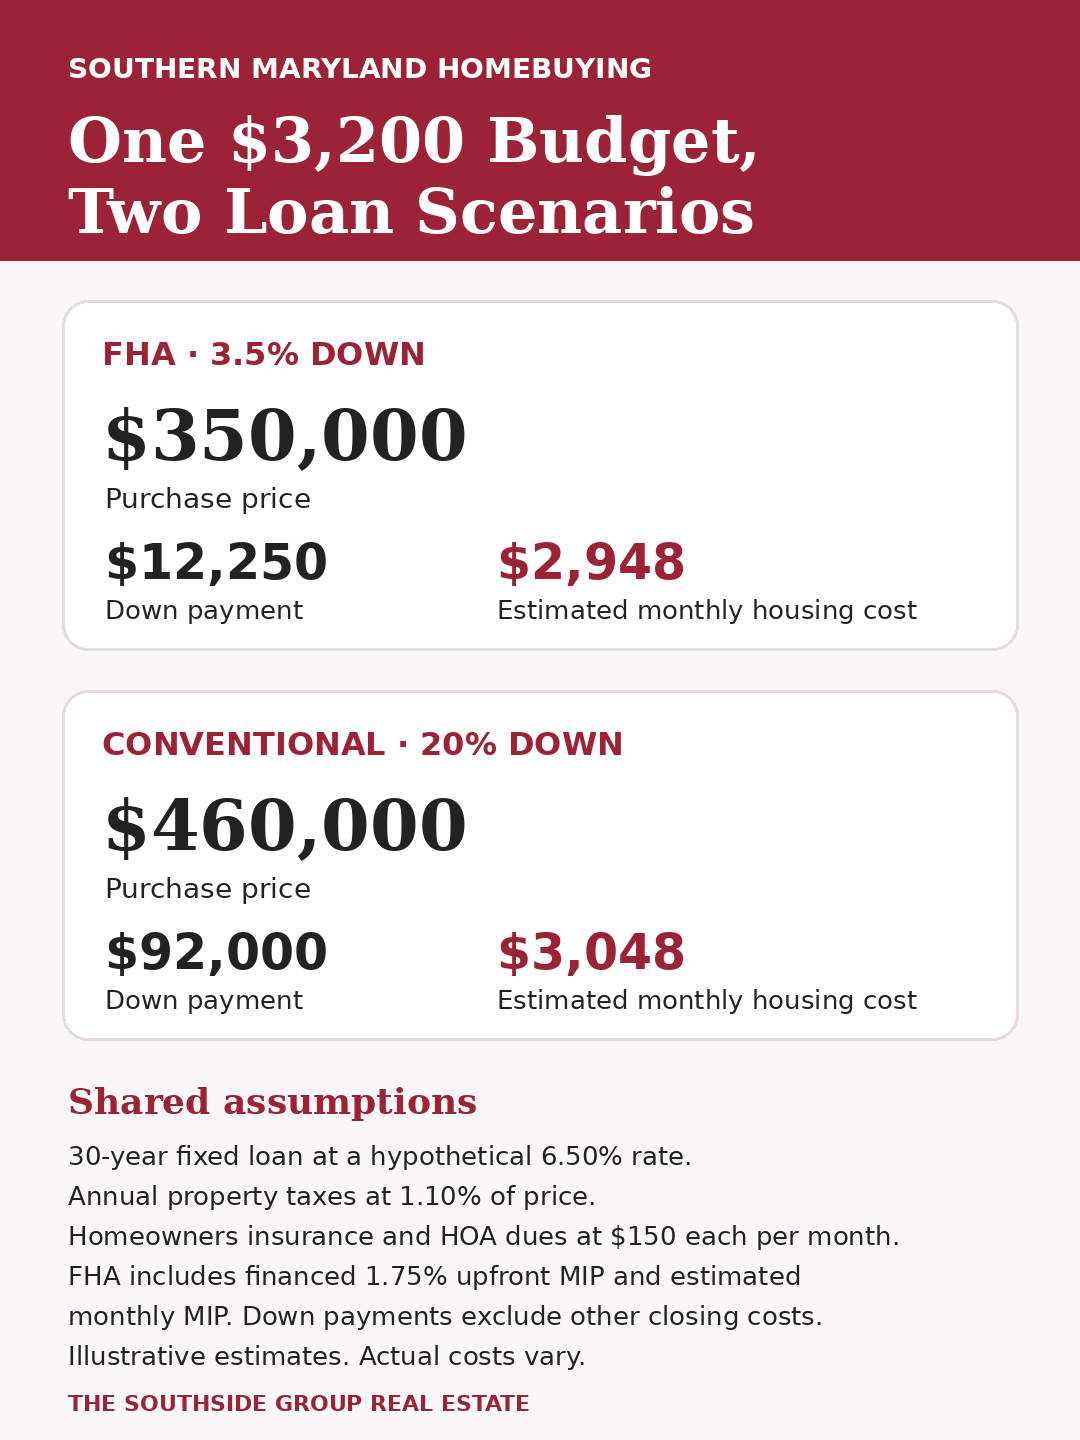
For example, under the assumptions below, a $350,000 home with 3.5% down comes to about $2,948 per month, while a $460,000 home with 20% down comes to about $3,048 per month. Both fit under $3,200 in this illustration, and the second requires $79,750 more for the down payment alone.
What Counts Toward Your Monthly Housing Budget?
Start with the loan’s principal and interest. Then add property taxes, homeowners insurance, any required mortgage insurance, and applicable HOA or condo dues. Include those dues in your budget even when the association bills them separately. Leave room in your household budget for utilities, maintenance, and repairs.
Track your upfront costs separately. In addition to a down payment, you may need money for closing costs, prepaid expenses, moving, and any immediate repairs. Decide how much savings you want to keep available after closing. If this is your first purchase, start with our first-time homebuyer resources.
How FHA and Conventional Loans Change the Math
FHA loans can allow down payments as low as 3.5% for eligible borrowers and generally include both upfront and annual mortgage insurance premiums. A conventional loan with 20% down typically avoids private mortgage insurance, or PMI. Comparing both options at the same assumed interest rate makes it easier to see how the amount borrowed, mortgage insurance, and down payment affect the numbers.
| Cost | FHA example | Conventional example |
|---|---|---|
| Purchase price | $350,000 | $460,000 |
| Down payment | $12,250 (3.5%) | $92,000 (20%) |
| Monthly principal and interest | $2,172 | $2,326 |
| Estimated monthly property taxes | $321 | $422 |
| Assumed monthly homeowners insurance | $150 | $150 |
| Estimated monthly mortgage insurance | $155 | $0 |
| Assumed monthly HOA dues | $150 | $150 |
| Estimated monthly housing cost | $2,948 | $3,048 |
Illustrative calculations only. Both examples assume a 30-year fixed loan at a hypothetical 6.50% interest rate and annual property taxes estimated at 1.10% of the purchase price. The FHA example finances a 1.75% upfront mortgage insurance premium and uses 0.55% of the base loan amount to approximate the early monthly mortgage insurance cost. Amounts are rounded. Actual rates, premiums, taxes, and dues vary. Down payments shown exclude other cash-to-close costs.
The down payment is where these two examples differ most. If you’re deciding how much cash to put down, ask a lender to compare options at the same purchase price as well. That comparison can show how using more of your savings would affect the payment on a home you’re actually considering.
Why Location Matters in Southern Maryland
Property tax rates vary by jurisdiction. A home in Leonardtown, Prince Frederick, or Waldorf can come with a different tax bill, insurance quote, and set of association dues. When you find a property you like, ask for its current tax information and any association dues, get an insurance quote for the address, and have your lender update the payment estimate.
That’s especially helpful when two homes have similar asking prices. One property’s recurring costs may leave more room in your budget for the features you care about. If you’re still narrowing down where to look, explore Southern Maryland communities.
How to Set Your Price Range Before You Shop
- Choose a monthly amount you can live with. Look at what remains after your regular expenses, savings, and expected home maintenance.
- Decide how much cash you want to use upfront. Account for closing costs and the savings you want available after the move.
- Talk to a lender early. Ask for estimates at a few purchase prices and down payments. Our mortgage preapproval guide explains where to start. Once you have property details and are comparing offers, review the Loan Estimates side by side.
- Build your search around that range. Set listing alerts for the areas and features you care about. When a home catches your eye, revisit the estimate with its actual costs in mind.
Frequently Asked Questions
Can I buy a $450,000 home with a $3,200 monthly budget?
Possibly. The monthly cost depends on your loan amount, interest rate, property taxes, homeowners insurance, mortgage insurance, and any association dues. Ask a lender to run the numbers for the specific address.
Do I need 20% down to buy a home in Maryland?
Some loan programs allow a smaller down payment. FHA loans can allow eligible borrowers to put down 3.5%, and some conventional loans also allow less than 20% down, typically with private mortgage insurance.
Does mortgage preapproval account for HOA dues?
Ask what your lender included in the estimate. Once you have a specific home in mind, give the lender the actual HOA or condo dues so they can factor them into the affordability calculation.
Start With a Budget You’re Comfortable With
Whether you’re buying soon or planning for next year, talk with The Southside Group Real Estate. We can connect you with a local lender and help you set up a home search around your budget and the features that matter most to you.
FROM OUR BLOG
Southern Maryland Housing Market Update | November 18, 2026
What is happening in the Southern Maryland real estate market this week? The latest Southern Maryland housing market update shows that buyers are still making moves, homes are going under contract, and price reductions may be creating opportunities for those searching for their next home. Across St.
Southern Maryland Home Warranty: What Is It and Is It Worth It?
Buying a home in Southern Maryland is exciting, but homeownership also comes with responsibilities. One of the biggest concerns for buyers is what happens when an expensive appliance or major home system breaks down shortly after moving in. A Southern Maryland home warranty may help with certain rep
Calvert County Events This Weekend | November 19–22, 2026
Calvert County events this weekend offer a wonderful mix of family-friendly activities, waterfront gatherings, hands-on workshops, holiday shopping, and local entertainment. From Thursday, November 19, through Sunday, November 22, 2026, communities throughout Southern Maryland have plenty of opportu